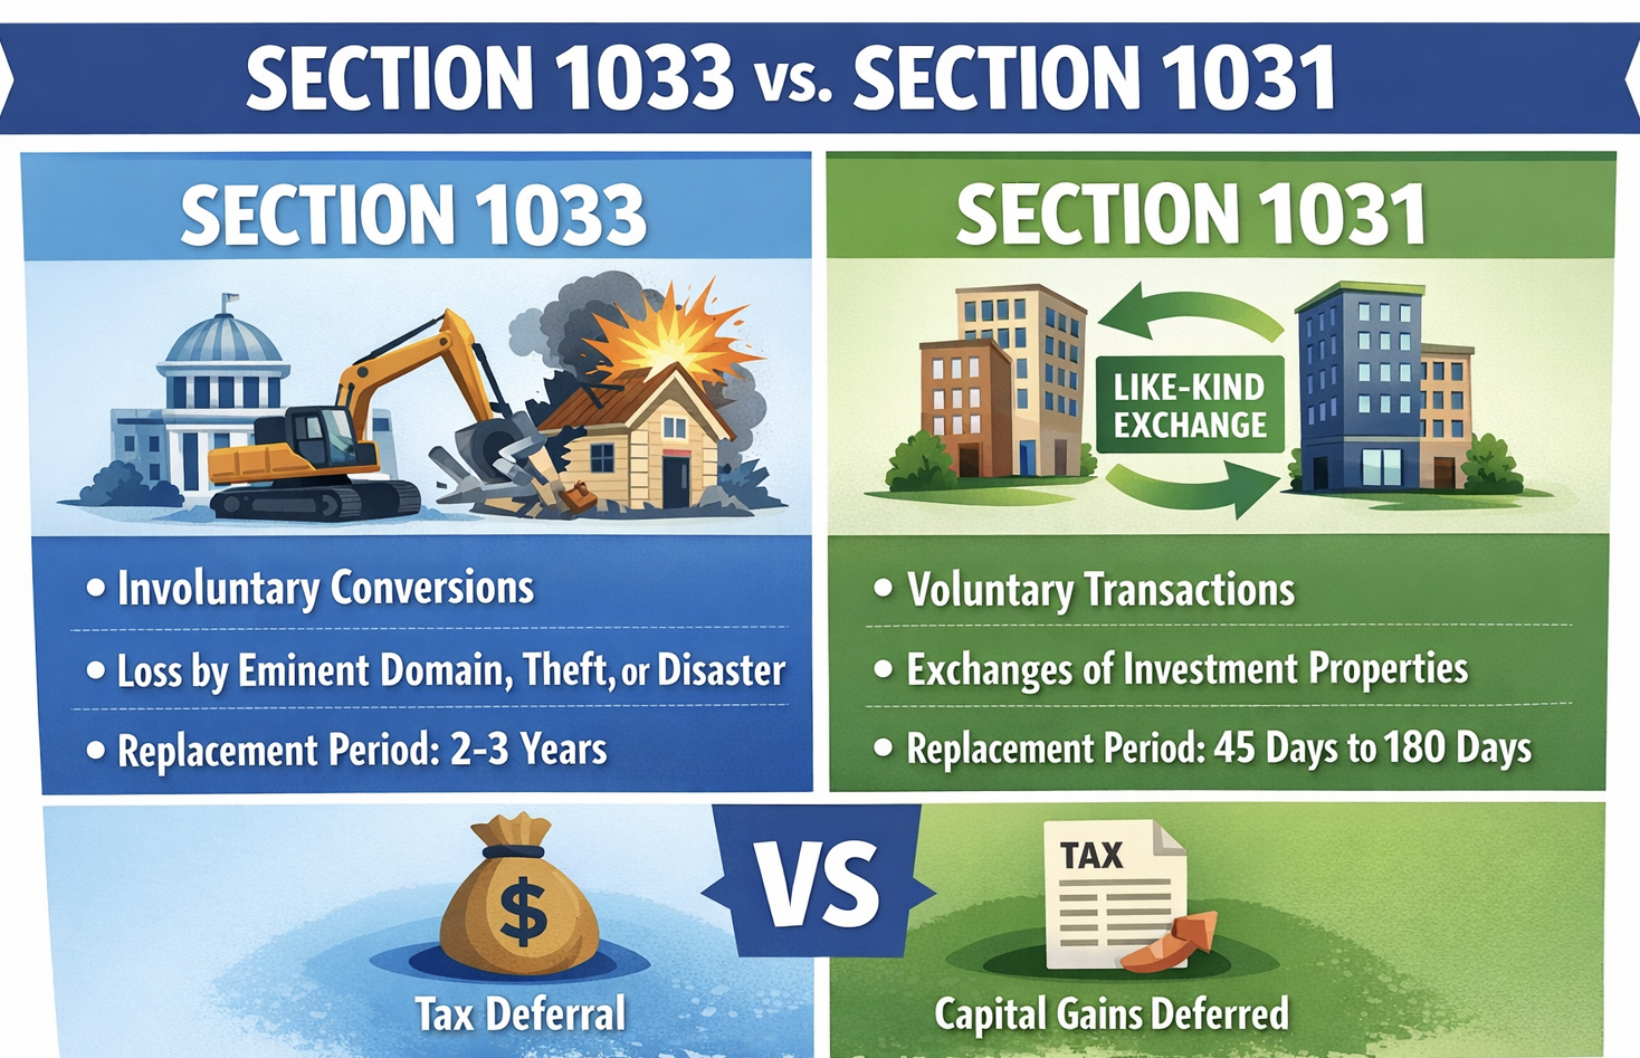
California capital gains tax on real estate has no discount: the Franchise Tax Board taxes every dollar of gain as ordinary income, at rates that reach 13.3% once taxable income passes $1 million. A 1031 exchange in California defers that state tax along with the federal bill, but the state keeps two hooks in the deal: 3 1/3% withholding at closing unless Form 593 claims the exchange exemption, and an annual FTB 3840 filing if your replacement property sits in another state.
Reviewed by Jon Hilley, CEO & Founder of 1031 Specialists. Last reviewed September 29, 2026.
| State tax on real estate gains | Ordinary income rates of 1% to 12.3%, plus a 1% Behavioral Health Services Tax on taxable income over $1,000,000 (13.3% top) |
|---|---|
| Long-term capital gains treatment | No lower rate and no exclusion; long-term and short-term gains are taxed the same |
| Nonresident withholding at closing | 3 1/3% of the sales price (or an elected gain-based amount), for residents and nonresidents alike |
| Withholding form | Form 593, Real Estate Withholding Statement; the 1031 exemption is claimed on it before closing |
| Transfer or conveyance tax (a 1031 does not defer it) | County documentary transfer tax of $0.55 per $500 ($1.10 per $1,000), plus city taxes such as Los Angeles (0.45% plus Measure ULA) and San Francisco (up to 6%) |
| Clawback on out-of-state replacement property | Yes. File FTB 3840 every year until the California-source deferred gain is recognized |
| Conforms to Section 1031 | Yes, limited to real property |
| Property tax note | Proposition 13: 1% base rate plus local bonds, reassessed at purchase, then capped at 2% a year |
Table of contents
- How much is capital gains tax on real estate in California?
- California tax on a $300,000 gain: worked example
- Form 593: California real estate withholding and the 1031 exemption
- California documentary transfer taxes a 1031 does not defer
- California conformity and the FTB 3840 clawback
- Proposition 13 and your replacement property
- Moving into or out of California
- Where California investors exchange
- Federal 1031 rules that apply in California
- California 1031 mistakes that cost real money
- Start your California 1031 exchange
- Frequently asked questions
- Sources
How much is capital gains tax on real estate in California?
California does not have a capital gains rate. The FTB states plainly that all capital gains are taxed as ordinary income, so the profit on a rental, a warehouse or a lot held for 20 years lands in the same brackets as wages. The 2025 schedules run from 1% to 12.3%, with the 12.3% bracket starting at $742,953 of taxable income for single filers and $1,485,906 for joint filers. On top of that, taxable income above $1,000,000 carries an extra 1% Behavioral Health Services Tax (formerly the Mental Health Services Tax), which is where the familiar 13.3% figure comes from.
A large sale often pushes an otherwise moderate earner into the top bracket for one year, because the whole gain is stacked into a single return. California also makes no separate allowance for depreciation: the portion of your gain created by past depreciation is simply part of the gain and is taxed at the same ordinary rates. Federally, that slice is unrecaptured §1250 gain taxed at up to 25%, and our depreciation recapture calculator estimates it.
There are no city or county income taxes in California, so the state line is the whole state bill. Federal tax still sits on top: 0%, 15% or 20% on long-term gain (20% above $545,500 single or $613,700 joint taxable income in 2026), plus the 3.8% net investment income tax above $200,000 single or $250,000 joint MAGI.
California tax on a $300,000 gain: worked example
Assumptions: a $300,000 long-term gain on an investment property, $100,000 of it from depreciation (unrecaptured §1250 gain), a married couple filing jointly who are already in the top federal bracket and whose income passes $1,000,000, so the 12.3% bracket and the 1% Behavioral Health Services Tax both apply.
| Line | Math | Tax |
|---|---|---|
| Federal: unrecaptured §1250 gain | 25% × $100,000 | $25,000 |
| Federal: remaining long-term gain | 20% × $200,000 | $40,000 |
| Federal: net investment income tax | 3.8% × $300,000 | $11,400 |
| Federal subtotal | $76,400 | |
| California: 12.3% top bracket | 12.3% × $300,000 | $36,900 |
| California: Behavioral Health Services Tax | 1% × $300,000 | $3,000 |
| California subtotal | No exclusion or deduction for capital gains | $39,900 |
| Total deferred by a full 1031 | $76,400 + $39,900 | $116,300 |
That $116,300 is roughly 39% of the gain. If your income stays under $1,000,000 the 1% tax drops away and the state line falls to about $36,900 at 12.3%, less for lower brackets. To see how a sale compares with exchanging, run the numbers in the capital gains vs. 1031 exchange comparison.
Form 593: California real estate withholding and the 1031 exemption
California withholds on the sale of real property whether the seller lives in Fresno or Florida. The default is 3 1/3% of the total sales price. A seller can instead elect the alternative withholding calculation, which applies 12.3% to the estimated gain for individuals and trusts (8.84% for corporations, 10.84% for banks and financial corporations, 13.8% for S corporations). Sales of $100,000 or less are exempt.
For an exchange, the seller certifies on Form 593 that the sale is part of an IRC §1031 exchange. The key rules from the FTB's 2026 instructions:
- A simultaneous exchange is exempt from withholding.
- In a deferred exchange, the qualified intermediary becomes the withholding agent and withholds only if you receive boot of more than $1,500 in cash or other property.
- If the exchange fails, the intermediary must withhold on the sale, based on the 3 1/3% or gain-based election you made.
- Withholding is remitted with Form 593 by the 20th day of the month after the month escrow closes.
- Since 2022, a cash-poor rule lets an intermediary limit withholding to the funds actually available in the exchange account.
On a $2,000,000 sale, a missed Form 593 exemption means $66,667 leaves escrow for the FTB instead of reaching your exchange account, and you wait until you file to recover it. Get the form to escrow before the closing date, not on it.
California documentary transfer taxes a 1031 does not defer
A 1031 exchange defers income tax only. Transfer taxes are due at recording on both the sale and the replacement purchase, and they are paid in cash from closing funds. In most counties the seller customarily pays, though it is negotiable.
- County documentary transfer tax: $0.55 per $500 of value ($1.10 per $1,000), computed on consideration net of any loan the buyer assumes.
- City of Los Angeles: a base tax of $2.25 per $500 (0.45%), plus the Measure ULA tax of 4% on sales above roughly $5.4 million and 5.5% above roughly $10.9 million. The thresholds are adjusted each July, so confirm the current figure with the city before you price a large sale.
- San Francisco: tiered rates of $2.50 per $500 up to $250,000, $3.40 up to $1 million, $3.75 up to $5 million, $11.25 up to $10 million, $27.50 up to $25 million and $30.00 above that. A $12 million building therefore pays 5.5% of the full price.
- Other cities: Culver City, Santa Monica, Pomona and Redondo Beach in Los Angeles County add their own rates, as do several Bay Area cities. Check the city where the deed records.
For an investor selling a $6 million Los Angeles property, the city base tax and ULA together run about 4.45% of the price, roughly $267,000, and none of it is deferred. Build it into your exchange math so the replacement purchase still covers the full net proceeds.
California conformity and the FTB 3840 clawback
California conforms to §1031 for real property. Since January 1, 2025 the state follows the federal limit to real property for everyone; the earlier window that let lower-income taxpayers exchange personal property has closed. A properly structured exchange defers the full California tax along with the federal tax.
The catch is geographic. California treats gain that built up on California soil as California-source income, no matter where you reinvest or later live. If you exchange California property for property outside the state, Form FTB 3840 is due with your California return for the year of the exchange and for each later year until that deferred gain is recognized. You file it even if you no longer owe any other California tax and must file a nonresident return just to attach it.
- The tracking continues through later exchanges. If your Texas replacement property is itself exchanged into Florida, the original California gain rides along and the 3840 filings continue.
- When you eventually sell in a taxable sale, California taxes its share of the original deferred gain.
- If you skip the form and do not file a return, the FTB can issue a Notice of Proposed Assessment for the deferred gain, plus penalties and interest.
Holding until death is the standard way the obligation ends, because heirs generally take a stepped-up basis. Our guide to swap till you drop covers that strategy.
Proposition 13 and your replacement property
California's property tax works differently from most states, and it matters when you pick a replacement property here. Proposition 13 limits the general levy to 1% of taxable value plus voter-approved bonds and assessments. Property is reassessed to market value at a change in ownership or new construction, and afterward the taxable value can rise by no more than 2% a year.
A 1031 exchange is a change in ownership for property tax purposes. The replacement property is reassessed at its purchase price, and your low base on the relinquished property does not transfer. Investors who have owned for decades often see the property tax on a same-size replacement double or triple. Budget for 1% plus local add-ons, which typically bring the effective rate to around 1.1% to 1.3% in major counties, and check for Mello-Roos or community facilities district charges in newer areas. The upside is predictability: once you buy, the base grows slowly.
Moving into or out of California
Nonresidents selling California property owe California tax on the gain, because real property is sourced to where it sits. Form 593 withholding applies to them too, and they report the sale on a nonresident return (Form 540NR).
Californians leaving the state often combine a move with an exchange into a no-income-tax state. That works for the federal tax, but the FTB 3840 follows the California-source gain. A common path is an exchange into Nevada or Arizona, with later gain on the new property taxed by the new state or not at all, while the original California gain stays tracked. Only appreciation after the exchange escapes California.
Investors moving into California should know that gain on out-of-state property you sell after becoming a resident is generally taxed by California in full at its ordinary rates. If you plan to sell a property in another state, weigh timing the sale or exchange before you establish California residency. Investors coming from Oregon face a similar tracking rule there.
Where California investors exchange
Exchange activity follows the state's largest metros, and each has its own mix of assets and transfer taxes:
- 1031 exchange in Los Angeles: multifamily and retail, with Measure ULA shaping pricing above the thresholds.
- 1031 exchange in San Francisco: small apartment buildings and mixed-use, where tiered transfer tax climbs quickly above $5 million.
- 1031 exchange in San Jose: Silicon Valley rentals and industrial.
- 1031 exchange in San Diego: coastal multifamily and investors trading into the Inland Empire.
- 1031 exchange in Sacramento: a frequent destination for Bay Area sellers seeking higher cap rates without leaving the state.
Many long-term California owners also exchange into passive holdings such as Delaware statutory trusts, which can be located out of state and still require the FTB 3840.
Federal 1031 rules that apply in California
Identify replacement property in writing within 45 days of closing and acquire it within 180 days. A qualified intermediary must hold the sale proceeds the entire time; if the money touches your account, the exchange fails. To defer all of the tax, buy property of equal or greater value and replace the debt you paid off, or add cash. Check your list with the 45-day identification validator, estimate the deferral with the 1031 exchange calculator, and see the 1031 exchange guides for detail.
California 1031 mistakes that cost real money
- Letting escrow close without the Form 593 exchange certification, so 3 1/3% of the price is withheld and stranded until you file.
- Forgetting FTB 3840 after moving out of state, which invites a Notice of Proposed Assessment on the full deferred gain years later.
- Leaving the Los Angeles ULA tax or San Francisco transfer tax out of the budget, then coming up short on the replacement purchase.
- Assuming the old Proposition 13 base carries over to the replacement property. It does not; the new property is reassessed at purchase.
- Taking cash out at closing above $1,500, which triggers withholding on the boot and taxable gain at California ordinary rates.
- Planning a sale for the year income crosses $1,000,000 without modeling the extra 1% Behavioral Health Services Tax.
Start your California 1031 exchange
Open the exchange before escrow closes so we can provide the exchange documents escrow needs for Form 593 and hold your proceeds in a segregated account. Start your exchange online, book an intro call, or call us at 631-438-1031. If you want to buy first and sell later, read about a reverse 1031 exchange.
Frequently asked questions
How can I avoid capital gains tax on real estate in California?
A 1031 exchange defers both the federal tax and California tax of up to 13.3% when you reinvest all proceeds in like-kind real property through a qualified intermediary. Holding until death, when heirs generally receive a stepped-up basis, can eliminate the deferred gain. A primary residence may qualify for the federal home sale exclusion, which California follows.
What is the California capital gains tax rate for 2026?
California has no separate capital gains rate. Gains are taxed as ordinary income at 1% to 12.3%, plus 1% on taxable income over $1,000,000, for a top rate of 13.3%.
Do I have to pay 3 1/3% withholding if I am doing a 1031 exchange?
No, if you certify the exchange on Form 593 before closing. In a deferred exchange the qualified intermediary withholds only on boot over $1,500, or on the sale if the exchange fails.
What is FTB 3840 and how long do I file it?
FTB 3840 is the annual information return for exchanging California real property into property outside California. You file it for the year of the exchange and every later year until the California-source deferred gain is recognized.
Does a 1031 exchange defer California transfer tax?
No. County documentary transfer tax and city taxes such as the Los Angeles base tax, Measure ULA and San Francisco transfer tax are due at recording and are not deferred by an exchange.
Will my replacement property keep my old Proposition 13 tax base?
No. A 1031 replacement is a change in ownership, so it is reassessed at its purchase price, with increases capped at 2% a year afterward.
Sources
- FTB: Capital gains and losses
- FTB: 2025 California tax rate schedules
- FTB: 2026 Form 540-ES instructions (1% tax over $1,000,000)
- FTB: 2026 Form 593 instructions
- FTB: Real estate withholding
- FTB: 2025 Form FTB 3840 instructions
- FTB: Reporting like-kind exchanges
- Los Angeles County Registrar-Recorder: Documentary transfer tax
- Los Angeles Office of Finance: Real property transfer tax and Measure ULA
- San Francisco Assessor-Recorder: Transfer tax
- Board of Equalization: California Property Tax, an Overview (Publication 29)
- IRS Topic 409: Capital gains and losses
Related: Nevada, Arizona, Oregon, Hawaii and all 50 states.
This page is general information for California sellers, not tax or legal advice. 1031 Specialists is a qualified intermediary; confirm rates, thresholds and forms with your CPA or attorney before you close.