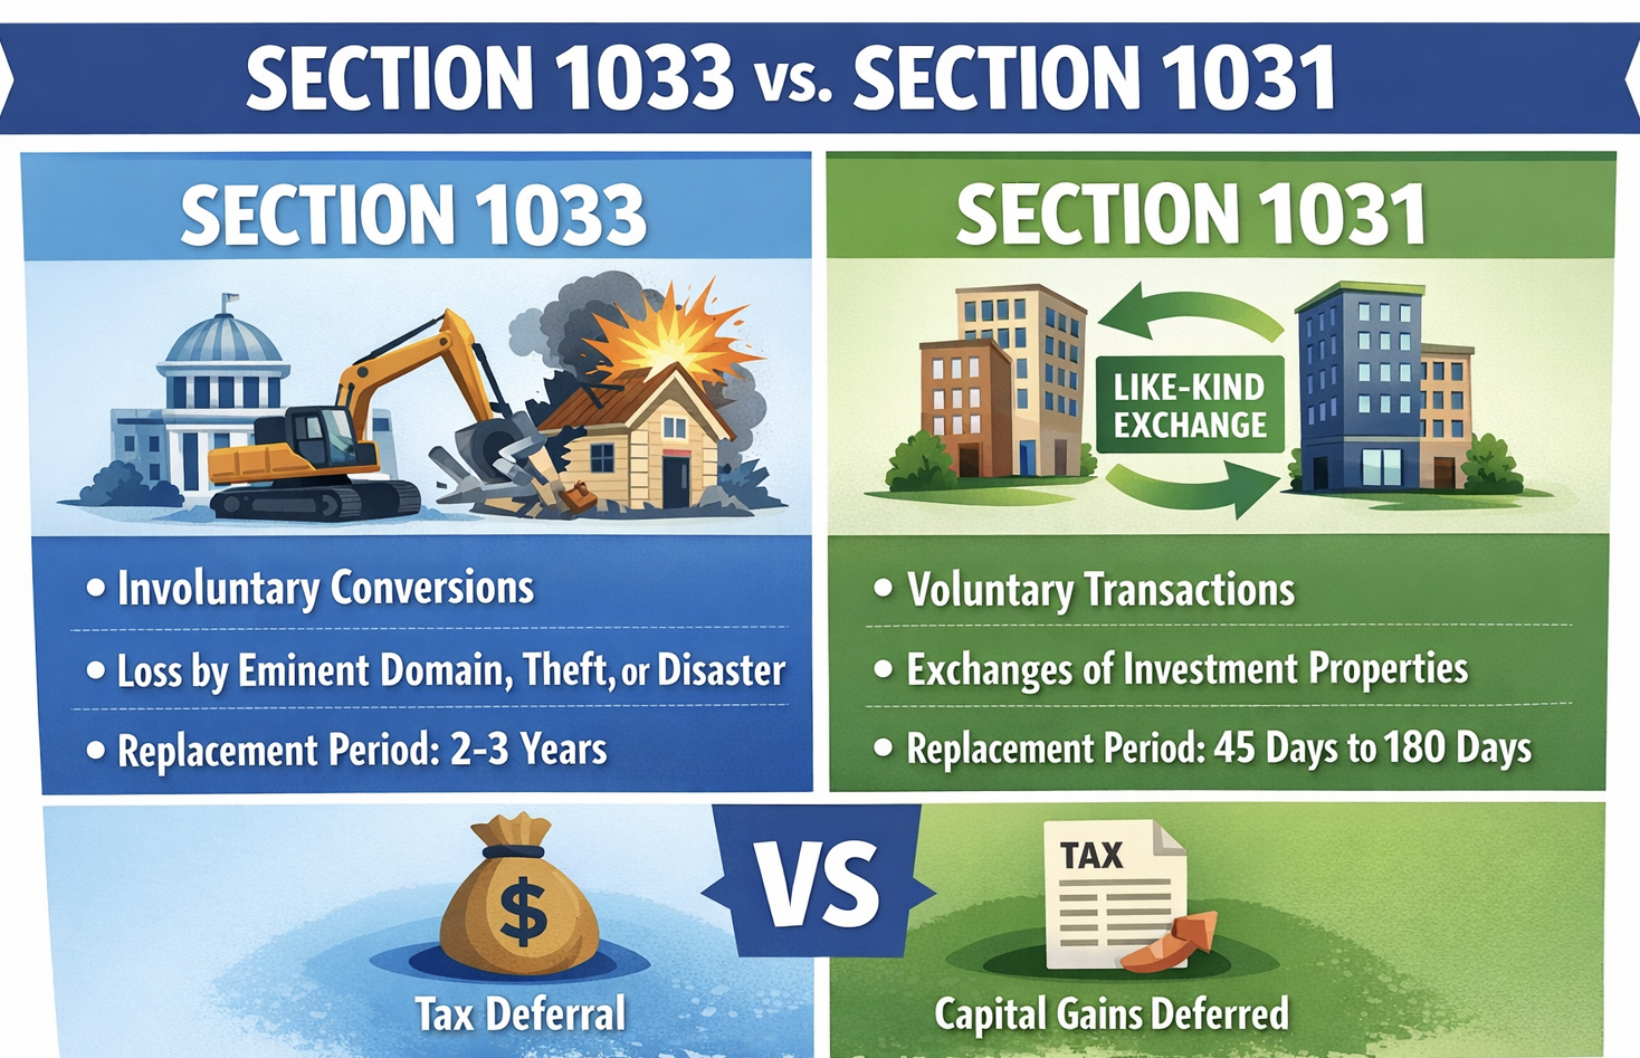
Texas capital gains tax on real estate is zero: the state has no personal income tax, and a 2019 constitutional amendment forbids the legislature from creating one. That leaves the federal bill, which on a long-held rental can take roughly a quarter of the gain, and that is exactly what a 1031 exchange in Texas defers. The state-level costs to plan for are local property taxes on the replacement property and, if you own through an LLC or partnership, the Texas franchise tax.
Reviewed by Jon Hilley, CEO & Founder of 1031 Specialists. Last reviewed September 29, 2026.
| State tax on real estate gains | None. Texas does not tax individual income, including capital gains. |
|---|---|
| Long-term capital gains treatment | No state tax for residents or nonresidents; only federal tax applies (0%, 15% or 20%, plus 3.8% NIIT and up to 25% on depreciation). |
| Nonresident withholding at closing | None at the state level. Foreign sellers still face federal FIRPTA withholding. |
| Withholding form | No Texas form required. |
| Transfer or conveyance tax (a 1031 does not defer it) | None. Texas has no state or local deed transfer tax; closing costs are title, escrow and recording fees. |
| Clawback on out-of-state replacement property | None. Texas has no income tax to recapture if you later exchange out of state. |
| Conforms to Section 1031 | Not applicable for individuals (no income tax). The exchange matters only on your federal return. |
| Property tax note | No state property tax, but local taxing units levy it on your replacement property; appraisal districts set values. |
Table of contents
- Is there a capital gains tax on real estate in Texas?
- Texas tax on a $300,000 gain: worked example
- Texas nonresident withholding: none at the state level
- Texas transfer taxes: there are none
- Conformity and clawback: why Texas has neither
- Texas franchise tax when an LLC or partnership sells
- Property tax on your Texas replacement property
- Moving into or out of Texas
- Where 1031 exchanges happen in Texas
- The federal rules for a Texas exchange
- Texas 1031 exchange mistakes to avoid
- Start your Texas 1031 exchange
- Frequently asked questions
- Sources
Is there a capital gains tax on real estate in Texas?
No. Texas has never had a personal income tax, and in 2019 voters approved Proposition 4, which added Section 24-a to Article VIII of the Texas Constitution: the legislature may not impose a tax on the net incomes of individuals, including an individual's share of partnership income. Reversing that would take another constitutional amendment, so the absence of a state tax on your gain is about as durable as tax law gets.
Because capital gains are income, the rule covers every piece of a real estate gain:
- Appreciation. No Texas tax, whether you held the property two years or twenty.
- Depreciation recapture. No Texas tax on the depreciation you claimed. Federally, it is still taxed at up to 25%.
- Nonresident owners. A Californian or New Yorker selling a Houston rental owes Texas nothing on the gain. Their home state may tax it, though.
- Local income tax. None. Texas cities and counties do not tax income.
So the Texas capital gains tax question has a one-word answer, and the real planning question is federal. For 2026, long-term gains are taxed at 0%, 15% or 20%, with the 20% rate starting above $545,500 of taxable income for single filers and $613,700 for joint filers. The 3.8% net investment income tax applies above $200,000 (single) or $250,000 (joint) of modified adjusted gross income. Our capital gains vs. 1031 exchange comparison shows the side-by-side for paying now versus deferring.
Texas tax on a $300,000 gain: worked example
Assumptions: you sell a Texas investment property for a $300,000 long-term gain, $100,000 of which is unrecaptured §1250 depreciation. You file jointly and are already in the top federal bracket. Texas adds nothing, so every dollar below is federal.
| Tax line | Amount |
|---|---|
| Unrecaptured §1250 gain: 25% of $100,000 | $25,000 |
| Long-term capital gain: 20% of $200,000 | $40,000 |
| Net investment income tax: 3.8% of $300,000 | $11,400 |
| Federal subtotal | $76,400 |
| Texas state income tax | $0 (no personal income tax) |
| Total tax deferred by a full 1031 exchange | $76,400 |
That $76,400 is the cost of selling outright. In a full exchange you reinvest all of it, and it keeps earning rent in the replacement property instead of going to the IRS. Run your own depreciation numbers in the depreciation recapture calculator; for many long-held Texas rentals the recapture line is larger than investors expect.
Compare the same gain in a high-tax state: a top-bracket California seller would owe a five-figure state tax bill on top of the same federal figure. Texas sellers avoid that line, which is why a Texas 1031 is purely a federal decision.
Texas nonresident withholding: none at the state level
Because there is no income tax, Texas has no withholding at closing, no seller residency affidavit and no exemption certificate to file before a 1031 closing. That is a genuine difference from states like California, Oregon or Hawaii, where the title company must hold back a percentage of the price unless you file for an exchange exemption in advance.
Two federal items still apply at a Texas closing:
- FIRPTA. If the seller is a foreign person, the buyer must generally withhold 15% of the amount realized for the IRS. An exchange can support a withholding certificate application, but it takes planning. See our guide to foreigners selling U.S. property under FIRPTA.
- Form 1099-S. The title company still reports the gross proceeds to the IRS. Your Form 8824 on the federal return is what shows the gain was deferred.
Nonresidents of Texas owe their home state, not Texas. A resident of a state with an income tax generally owes that state tax on a Texas sale unless the home state follows the federal exchange rules.
Texas transfer taxes: there are none
Texas does not charge a real estate transfer tax, deed tax, documentary stamp tax or mansion tax, at the state level or in any city or county. In states such as Washington, New York or Pennsylvania, transfer taxes can add 1% to 4% of the price on each side of an exchange, and a 1031 does not defer them. In Texas that line is simply absent.
What you do pay at closing:
- Title insurance premiums for the owner's policy, customarily paid by the seller in many Texas markets.
- Escrow and closing fees charged by the title company.
- County clerk recording fees for the deed and deed of trust, typically a modest flat charge per page.
- Prorated property taxes for the year of sale, since Texas property taxes are paid in arrears.
Paying ordinary closing costs from exchange funds is generally fine. Using exchange funds for loan fees or prorated rent credits can create taxable boot, so review the settlement statement with your intermediary.
Conformity and clawback: why Texas has neither
Income tax states must decide whether to follow Section 1031, and a few (California, Oregon, Montana, Massachusetts) track deferred gain when you exchange into another state. Texas has no individual income tax to conform, so there is no Texas form to file on the exchange and nothing for Texas to claw back later.
The flip side matters if you are moving here. A Texas residence does not erase another state's claim. California, for example, requires annual FTB 3840 filings when a Californian exchanges into out-of-state property and taxes the deferred California gain when the replacement is eventually sold, even if you now live in Austin.
Texas franchise tax when an LLC or partnership sells
Texas has no income tax on people, but it does levy a franchise (margin) tax on most entities formed or doing business in Texas. Many investors hold rentals in an LLC or limited partnership, so the entity's report is the one Texas return that can be touched by a sale.
- 2026 and 2027 reports: the no-tax-due threshold is $2,650,000 of annualized total revenue. Most single-property LLCs fall under it.
- Rates: 0.75% of taxable margin for most businesses, 0.375% for qualifying retail and wholesale.
- Sale year: a large sale can push revenue over the threshold for that year. How gain enters total revenue and whether a passive-entity exception applies to your structure is a question for your CPA before closing.
An exchange does not change who the taxpayer is: the LLC that sells must be the LLC that buys. If you plan to restructure ownership, do it well before or after the exchange, not in the middle.
Property tax on your Texas replacement property
Texas funds schools and local government largely through property tax, so it is usually the biggest recurring cost on a Texas replacement property. There is no state property tax; counties, cities, school districts and special districts each set a rate, and the local appraisal district sets the value.
- Underwrite on the next bill, not the seller's. A property that just sold often gets reappraised closer to its price. Base your pro forma on current local rates applied to your purchase price.
- Protest every year. Owners can protest the appraisal district value to the Appraisal Review Board. The deadline is generally May 15 or 30 days after the notice is delivered, whichever is later.
- Special districts. Suburban MUDs around Houston, Dallas-Fort Worth and Austin can add meaningfully to the combined rate. Check the full list of taxing units on the tax certificate.
Higher property tax is the price of no income tax. A Texas replacement with a 7% cap rate before tax can land well lower after a realistic tax line, so the yield comparison with a lower-tax state deserves real numbers.
Moving into or out of Texas
Moving in. Texas is a top destination for exchange dollars from high-tax states. A Texas replacement property shelters the gain federally, but your old state may keep a claim. A Californian exchanging into Texas files FTB 3840 each year and owes California when the Texas property is sold in a taxable sale. Oregon has a similar OR-24 regime. Read our California 1031 exchange page before listing a California property to buy in Texas.
Moving out. Texans selling here and buying in another state carry no Texas baggage, but the new state taxes any later sale of property located there. Buying in Oklahoma or New Mexico means that state's income tax applies when you eventually cash out, whatever your residence.
Estate angle. Texas has no estate or inheritance tax. Investors who hold exchanged property until death can pass it with a stepped-up federal basis, a strategy often called swap till you drop.
Where 1031 exchanges happen in Texas
Texas exchange activity spreads across four major metros and a long list of fast-growing secondary cities.
- Dallas-Fort Worth leads in industrial, multifamily and single-tenant retail. See our guide to a 1031 exchange in Dallas-Fort Worth.
- Houston offers energy-linked office, a deep industrial market along the port and ship channel, and large apartment inventory. See 1031 exchange in Houston.
- Austin saw heavy multifamily and build-to-rent development; recent new supply makes rent assumptions worth testing. See 1031 exchange in Austin.
- Abilene and West Texas appeal to investors trading down in price per door or into farm and ranch land. See 1031 exchange in Abilene.
San Antonio, the Rio Grande Valley and Midland-Odessa round out the list. Farm and ranch land exchanges are common in Texas and qualify as like-kind to rental buildings, since any U.S. investment real estate counts.
The federal rules for a Texas exchange
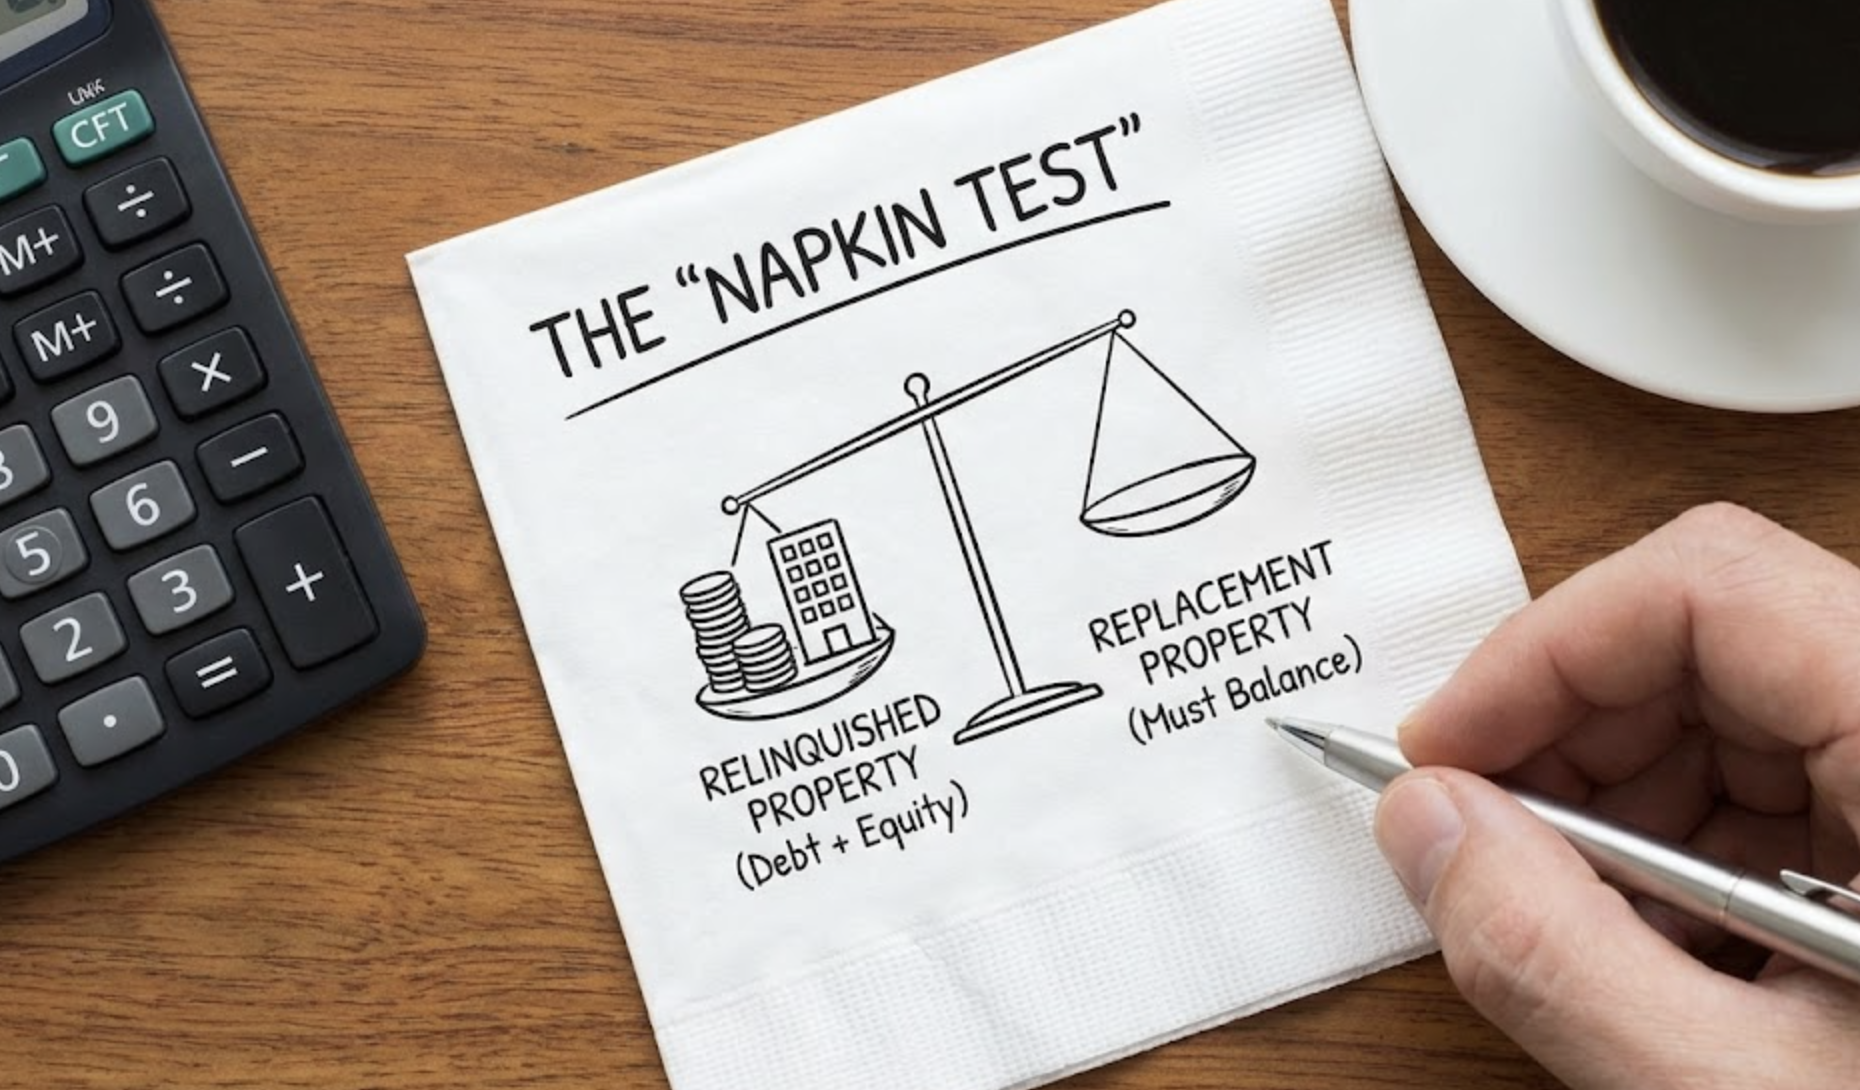
From the day your Texas sale closes you have 45 days to identify replacement property in writing and 180 days to close on it. A qualified intermediary must hold the sale proceeds; touching the funds ends the exchange. To defer all of the federal tax, buy at least as much as you sold and replace the debt you paid off. Our 1031 exchange guides cover the details, the 45-day identification validator checks your list, and the 1031 exchange calculator estimates what you defer.
Texas 1031 exchange mistakes to avoid
- Skipping the exchange because "Texas has no capital gains tax." The state line is zero, but the federal line on a long-held rental can exceed 25% of the gain.
- Underwriting the replacement on the seller's tax bill. A reappraisal after your purchase can raise the property tax line and cut the yield you counted on.
- Changing the LLC mid-exchange. Dissolving, merging or adding members between the sale and the purchase can break the same-taxpayer requirement and complicate the franchise tax report.
- Forgetting your former state. New Texans who exchanged out of California or Oregon still owe that state's tracking filings and tax on a later taxable sale.
- Letting a hot market rush identification. Competitive DFW and Austin deals tempt buyers to identify one property. Name backups, or consider a reverse exchange if you must buy first.
Start your Texas 1031 exchange
Open your exchange with 1031 Specialists before the Texas sale closes, so the title company wires proceeds to us and your deadlines start cleanly. You can start your exchange online, book a free intro call, or call (631) 438-1031. We prepare the exchange agreement and assignment documents, coordinate with your Texas title company and hold funds in a segregated account until your replacement closes.
Frequently asked questions
Does Texas have a capital gains tax on real estate?
No. Texas has no personal income tax, and Article VIII, Section 24-a of the Texas Constitution bars the legislature from taxing individual net income. You still owe federal capital gains tax, the 3.8% net investment income tax and up to 25% on depreciation recapture.
How can I avoid capital gains tax on real estate in Texas?
There is no Texas tax to avoid. To defer the federal tax, complete a 1031 exchange: have a qualified intermediary hold the proceeds, identify replacement property within 45 days, close within 180 days and buy equal or greater value while replacing your debt. Holding exchanged property until death can also give heirs a stepped-up basis.
Is there withholding or a transfer tax when I sell property in Texas?
No. Texas has no state withholding on real estate sales and no state or local transfer tax. Foreign sellers are still subject to federal FIRPTA withholding, generally 15% of the amount realized.
Is a 1031 exchange worth it in Texas if there is no state tax?
Usually yes for long-held property. On a $300,000 gain with $100,000 of depreciation, a top-bracket joint filer would owe about $76,400 in federal tax, all of which a full exchange defers.
Does the Texas franchise tax apply when my LLC sells property?
It can. The franchise tax applies to most LLCs and partnerships, with a no-tax-due threshold of $2,650,000 of annualized revenue for 2026 and 2027 reports. A large sale can affect that year’s report, so ask your CPA how your entity will report the sale.
Can I exchange California property into Texas property?
Yes. Any U.S. investment real estate is like-kind. California will still track the deferred California gain through annual FTB 3840 filings and tax it when the Texas property is later sold in a taxable sale.
Sources
- Texas Legislative Council: analyses of 2019 constitutional amendments (Proposition 4)
- Texas Comptroller: property tax
- Texas Comptroller: property tax protests and appeals
- Texas Comptroller: franchise tax rates and thresholds
- IRS: like-kind exchanges, real estate tax tips
Related: Oklahoma, Louisiana, New Mexico, Arkansas, all 50 states.
This page is general information, not tax or legal advice. 1031 Specialists is a qualified intermediary; confirm your own situation with a CPA or tax attorney before you sell.