Most Colorado real estate that goes through a 1031 exchange is owned by someone who doesn't live in Colorado. That one fact drives the two Colorado-specific steps in an exchange: the withholding the title company takes from a nonresident seller at closing unless the exchange is certified in advance, and the second-home and short-term-rental economics that shape the resort markets. Colorado's flat income tax is low, its statewide transfer fee is close to zero, and its property tax depends less on where a building is than on what class it's in. In the mountain towns, all three of those change. We act as your qualified intermediary, hold the proceeds, and handle the Form DR 1083 certification with your title company so nothing is withheld that shouldn't be.
Table of contents
- Colorado's 2% nonresident withholding and how an exchange avoids it
- What Colorado taxes when you sell investment property
- Colorado conforms to Section 1031
- Transfer taxes: a $500 fee statewide, 1% to 3% in the resort towns
- Property tax: the class gap and metropolitan districts
- Short-term rental rules in the resort markets
- The federal deadlines, applied to a Colorado closing
- Colorado markets
- The California corridor and other cross-state exchanges
- Mistakes we see in Colorado exchanges
- Start your Colorado 1031 exchange
- Frequently asked questions
Colorado's 2% nonresident withholding and how an exchange avoids it
When a nonresident sells Colorado real property for more than $100,000, the title company must withhold the lesser of 2% of the sales price or the seller's net proceeds and send it to the Department of Revenue with Form DR 1079. The seller recovers it as a payment on a Colorado nonresident return the following year. It isn't an additional tax, but in an exchange it's cash that should have gone to your intermediary and instead sits with the state for up to a year, and it can leave you short at the replacement closing. On a $1.5 million sale that's $30,000.
Form DR 1083 is how you avoid it. It's the affirmation the seller signs at closing stating why withholding doesn't apply, and one of the listed reasons is that the property is being transferred in a like-kind exchange in which no gain is recognized. Your exchange documents are the support for that affirmation. Three practical points:
- The title company has to know it's an exchange before the settlement statement is drafted. We send the exchange agreement, the assignment, and the notice to the closer as soon as you engage us and confirm the DR 1083 treatment with them directly.
- Partial exchanges are the gray area. If you're taking cash out, the recognized gain isn't zero and the closer may withhold on the boot. Settle the amount of any boot with your CPA before closing so the withholding, if any, is calculated on the right number. Our partial exchange calculator gives you that figure.
- Entity sellers are handled differently. If the property is held in an LLC, partnership, trust, or corporation, the transferor for DR 1083 purposes is the entity, and whether withholding applies depends on the entity type and whether it's registered in Colorado. Confirm with the closer early rather than at the table.
What Colorado taxes when you sell investment property
Colorado taxes the gain as ordinary income at a single flat rate, 4.40% by statute. There are no brackets and no separate capital gains rate, and the old Colorado capital-gain subtraction for long-held Colorado assets has been narrowed to qualifying agricultural land, so investment real estate gets no state break. The flat rate has been temporarily lowered in some recent years when TABOR surpluses triggered a one-year reduction (4.25% for tax year 2024), so the rate on an eventual taxable sale is set by the year of that sale; for planning, use 4.40%. Nonresidents owe it on Colorado-source gain and file Form DR 0104 with the DR 0104PN nonresident schedule.
The federal stack on the same sale is where most of the money is: long-term capital gains at 15% or 20% (the 20% bracket starts at $545,500 of taxable income for single filers and $613,700 for joint filers in 2026), the 3.8% net investment income tax, and 25% on depreciation recapture. Colorado's 4.40% on a $2 million gain is $88,000; the federal tax on the same gain can run four to six times that. A properly structured exchange defers all of it. Our capital gains vs. 1031 comparison shows the full stack for your numbers and the depreciation recapture calculator isolates the recapture piece.
Colorado conforms to Section 1031
Colorado's income tax starts from federal taxable income and does not decouple from Section 1031. Gain deferred on your federal return is deferred for Colorado automatically, with no state election and no annual tracking form. The withholding step above is the only place Colorado inserts itself into an exchange, and it's a timing issue, not a substantive one. When you eventually sell the replacement property without exchanging, Colorado taxes the deferred gain if you're a resident then, or to the extent the final property is in Colorado if you're not.
Transfer taxes: a $500 fee statewide, 1% to 3% in the resort towns
Colorado's statewide documentary fee is one cent per $100 of consideration, $500 on a $5 million sale, and the 1992 TABOR amendment barred new real estate transfer taxes. What survived is the transfer taxes the resort towns already had on the books, which were grandfathered and remain among the highest in the country: Aspen 1.5%, Avon 2%, Breckenridge 1%, Crested Butte 3%, Frisco 1%, Snowmass Village 1%, Telluride 3%, Vail 1%, and Winter Park 1%, with a handful of smaller mountain towns between 1% and 4%. In most of these the buyer pays. A 1031 exchange doesn't defer any of it. On a $4 million Telluride replacement property that's $120,000 at closing. Transfer tax is generally treated as an exchange expense, so it can be paid from exchange funds without creating boot, but it's $120,000 that isn't going into the building. Price it into your identification, and confirm the current rate and which party pays with the town before you sign.
Property tax: the class gap and metropolitan districts
Colorado property tax is two numbers multiplied together: an assessment rate set statewide by property class, and a mill levy set by the taxing districts the parcel sits in. The assessment rate is what surprises investors from other states. Residential property, which includes apartment buildings, is assessed at roughly 6.7% of actual value. Nonresidential property, meaning office, retail, industrial, and lodging, is assessed at about 27%, stepping down toward 25% by 2027 under the 2024 property tax legislation. Same value, same mill levy, and the commercial building pays roughly four times the tax. At 80 mills, a $5 million apartment building is assessed at $335,000 and pays about $26,800 a year; a $5 million office or retail building is assessed at $1.35 million and pays about $108,000. That gap is priced into Colorado cap rates, which is why a commercial cap rate that looks generous next to multifamily may be taxes rather than opportunity.
The second surprise is metropolitan districts. Much of the development since the 1990s in the Denver suburbs, Douglas and Adams counties, and Northern Colorado sits inside a metro district that issued bonds to build its own infrastructure and services that debt through an additional mill levy on top of county, school, city, and special-district mills. Total levies above 100 mills inside a district, against 60 to 80 outside one, are common. Countywide averages hide this. Pull the certified levy for the specific parcel from the county assessor before you underwrite.
Third, a policy risk: short-term rentals are currently assessed as residential. Bills to reclassify them as lodging at the commercial rate have been introduced in recent sessions and failed. If your resort pro forma depends on the residential assessment rate, that's a four-times exposure if the legislature changes its mind.
Short-term rental rules in the resort markets
Resort returns often depend on nightly rental income, and Colorado's mountain towns have spent the last several years restricting it. The mechanism differs by town, so the answer has to be checked at the parcel level, but the categories are:
- License caps by zone, with waitlists. Breckenridge and unincorporated Summit County cap the number of licenses in their residential zones; outside the exempt resort zones, a new owner may wait years or never get one.
- Overlay zones. Steamboat Springs prohibits new short-term rentals outside designated overlay areas and adds a 9% tax on short-term stays on top of sales and lodging tax.
- Permit categories with local excise taxes. Aspen issues different permit classes for owner-occupied and non-owner-occupied rentals and layers a short-term rental tax of up to 10% on the latter. Vail requires registration and has tightened enforcement on parking, occupancy, and noise.
- Moratoria and caps in the smaller towns, including Crested Butte and Telluride at various points.
The underwriting rule that follows: a license generally does not transfer with the property. Before you identify a resort replacement, confirm that a new owner can get a license at that address, how long it takes, and what the all-in tax on a nightly stay is. If the answer is no new licenses in that zone, the asset is a long-term rental or a second home and the pro forma should say so.
One more point that is federal but bites hardest in Colorado resorts. A vacation property qualifies for an exchange only if it's held for investment, not personal use. The IRS safe harbor in Revenue Procedure 2008-16 is that in each of the two years before the sale and the two years after the purchase, the property is rented at fair market value for at least 14 days and your personal use doesn't exceed the greater of 14 days or 10% of the days rented. A Breckenridge condo the family uses every Christmas week and most of ski season can fail that test. Keep the rental calendar.
The federal deadlines, applied to a Colorado closing
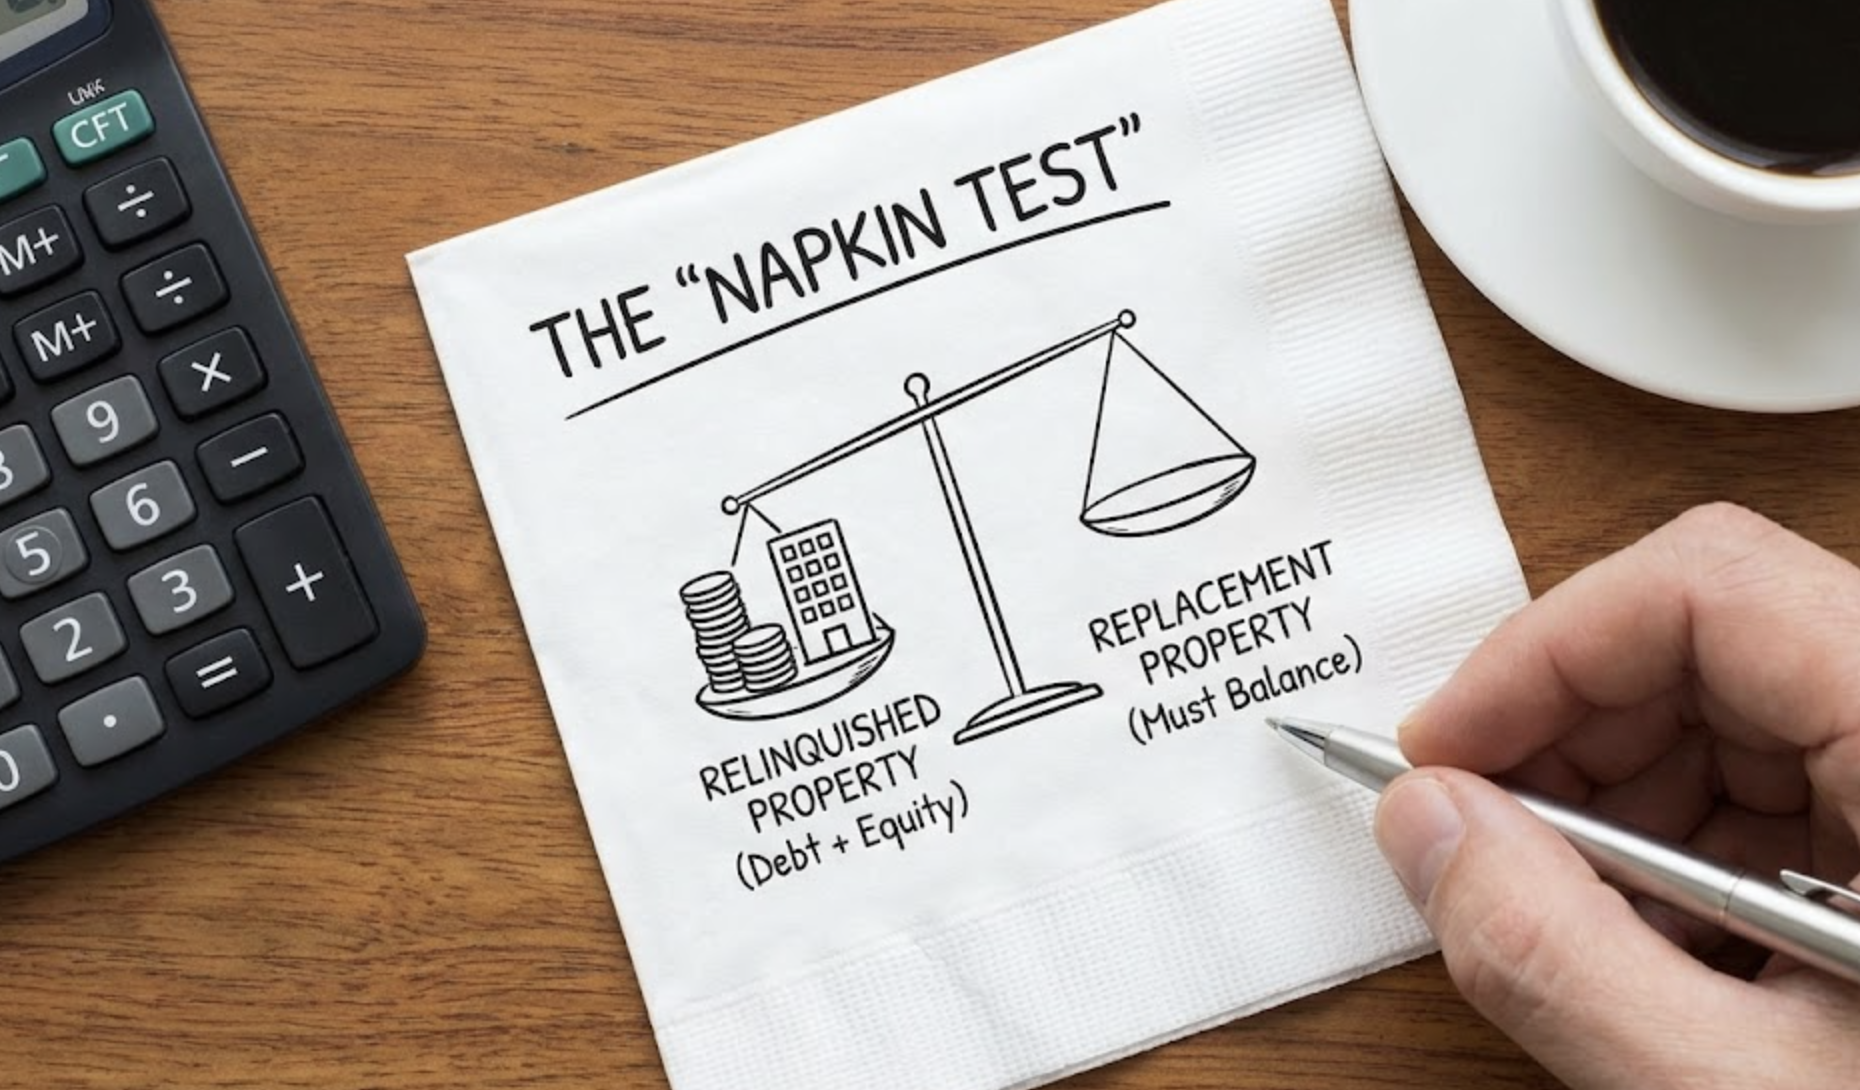
The 45-day identification and 180-day exchange periods are federal and run from the date your relinquished property closes. Our deadline tracker calendars both and the 45-day identification validator checks your list against the identification rules. Colorado closings are run by title companies rather than attorneys, so the title company's closer is who we coordinate with on the exchange documents and the DR 1083, and the sequence matters: exchange agreement signed and assignment delivered before closing, the DR 1083 affirmation prepared alongside the settlement statement, proceeds wired from the closer to us and never to you. The entity that sells must be the entity that buys, and the reinvestment has to match or exceed the relinquished property's value and debt or the difference is taxable boot. Wire fraud targeting exchange funds is a real risk in high-value resort closings; run our wire-fraud prevention checklist with your closer before any funds move.
In resort inventory, the replacement property often has to be tied up before the sale closes. A reverse exchange, where we park the replacement property with an exchange accommodation titleholder until your sale closes, is common in Summit, Eagle, and Pitkin counties for that reason, and it has to be set up before you go under contract on the purchase, not after.
Colorado markets
Denver and its suburbs carry most of Colorado's exchange volume. Multifamily absorbed a large wave of new deliveries over the last few years, which has pushed exchangers toward value-add and suburban product rather than new Class A; industrial along I-70, I-76, and E-470 near the airport remains the deepest institutional market in the state; downtown office is the weakest asset class and is where the conversion and distressed opportunities are. Colorado Springs runs on defense and the military installations and offers multifamily at lower entry prices; Fort Collins and Loveland ride Colorado State University and Northern Colorado's growth; Boulder is life sciences, tech, and the most expensive submarket outside the resorts. Grand Junction anchors the Western Slope at prices that let smaller exchangers buy whole buildings. The resort markets, Aspen and Snowmass, Vail and Beaver Creek, Breckenridge and the rest of Summit County, Steamboat Springs, Telluride, and Crested Butte, are a separate Colorado story with the highest values in the state, the highest transfer taxes, and the short-term rental regime described above.
The California corridor and other cross-state exchanges
California to Colorado is the corridor. California sellers exchange out of the state's 13.3% top rate into Denver multifamily and the resort markets every year, and there is a California-specific consequence to understand: California follows the deferred gain. For as long as you hold the Colorado replacement property, California requires an annual information return on Form FTB 3840, and when you eventually sell in a taxable sale, California taxes the California-source portion of the gain even if you've been a Colorado resident for a decade. Colorado has no equivalent. Our California 1031 guide covers the sale-side rules, including California's own nonresident withholding. Texas and Arizona sellers are the next largest inbound group; outbound, Colorado owners most often exchange into Wyoming, an hour north of Fort Collins with no state income tax, or into Texas. And if the seller of a Colorado resort property is a foreign person, FIRPTA's federal withholding applies alongside DR 1083; our FIRPTA guide explains how the two interact.
Mistakes we see in Colorado exchanges
- Letting the title company withhold 2% because no one told the closer it was an exchange until the settlement statement was final.
- Underwriting a resort replacement on short-term rental income without confirming a new owner can get a license at that address.
- Comparing a commercial cap rate to a multifamily cap rate without adjusting for the 27% versus 6.7% assessment gap.
- Missing a metro-district levy by using the county average.
- Forgetting the 1% to 3% resort transfer tax on the purchase side of the exchange.
- Using a vacation property too much personally to meet the investment-use safe harbor.
- The universal ones: taking receipt of the proceeds, missing the 45th day, or trading down into boot. If the exchange does fail, our tax-straddling guide explains how to push recognition into the following tax year.
Start your Colorado 1031 exchange
Engage us before the relinquished property closes so the exchange documents and the DR 1083 affirmation reach the title company in time. We prepare the exchange agreement, assignment, and notice, confirm the withholding treatment with your closer, hold the proceeds in a segregated, bonded account under the 1031 Specialists Standard, calendar the 45- and 180-day deadlines, and coordinate the replacement closing in Colorado or any other state. Book a call to walk through a specific Colorado deal, or call (631) 438-1031.
Frequently asked questions
Is there withholding when a nonresident sells Colorado property?
Yes. On sales over $100,000 the title company withholds the lesser of 2% of the price or the net proceeds and remits it on Form DR 1079. In a 1031 exchange the seller affirms on Form DR 1083 that no gain is recognized, and nothing is withheld.
What is Colorado's tax rate on real estate gains?
A flat 4.40% by statute, applied to the gain as ordinary income, on top of federal capital gains tax, the 3.8% net investment income tax, and depreciation recapture. TABOR surpluses have temporarily lowered the rate in some years. A 1031 exchange defers the state and federal tax together.
Does Colorado have a real estate transfer tax?
Statewide, only a documentary fee of one cent per $100. Grandfathered transfer taxes of 1% to 3% apply in resort towns including Aspen, Vail, Breckenridge, Telluride, and Crested Butte, usually paid by the buyer, and an exchange doesn't defer them.
Can I 1031 into a short-term rental in Breckenridge or Aspen?
Yes, if it's held for investment and rented at fair market value, with your personal use inside the IRS safe harbor. The practical constraint is licensing: confirm a new owner can get a short-term rental license at that address before you identify it.
I'm selling in California and buying in Denver. What does California do?
California requires an annual Form FTB 3840 for as long as you hold the Colorado property and taxes the California-source gain when you eventually sell without exchanging. Colorado has no tracking requirement of its own.
Do I need a qualified intermediary for a Colorado exchange?
Yes. The exchange is only valid if a qualified intermediary holds the proceeds between closings, and the intermediary can't be your agent, attorney, or a relative. In Colorado the intermediary's documents also support the DR 1083 affirmation, so engage one before the sale closes.
This page is general information, not tax or legal advice. We act as a qualified intermediary and do not provide tax or legal advice. State and federal rules, rates, and thresholds change; confirm current figures with your tax advisor.
Colorado 1031 resources and nearby states
Neighboring states
Where Colorado buyers come from
- 1031 exchange in California — FTB 3840 follows the deferred gain
- 1031 exchange in Texas — no state income tax
- 1031 exchange in Arizona